
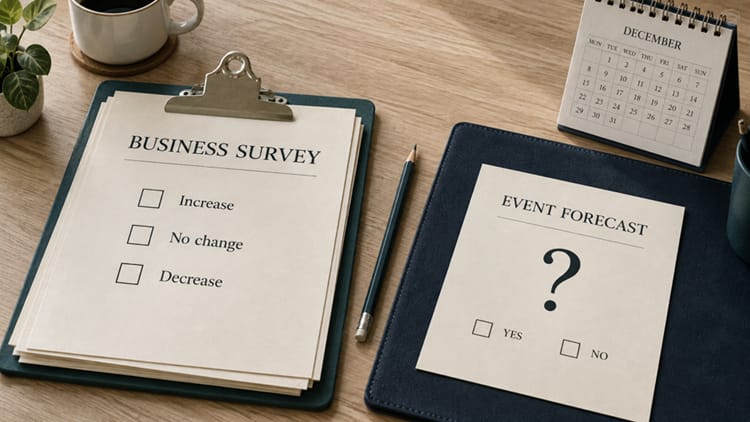
A business owner can encounter two apparently conflicting percentages before finishing the morning news: a survey suggests firms are cautious, while a market puts a high probability on an economic event. Calling one optimistic and the other pessimistic may miss what each measures. A business survey can describe how many respondents expect their own sales to change. A prediction market can concern whether one precisely defined event happens. The percentage sign alone does not identify which kind of answer you are reading.
The British Chambers of Commerce’s Q2 2026 survey found that 44% of responding businesses expected their turnover to improve over the following 12 months. More than 4,700 businesses across the UK responded, with small and medium-sized enterprises making up 92% of the sample. Fieldwork ran from 11 May to 8 June 2026, and the findings were published on 5 July.
A probability in prediction markets news needs a different reading. It is generally an estimate inferred from the traded price of a contract about a defined event. That event might concern an economic figure crossing a stated threshold by a specified date. The percentage belongs to that question; it does not count the firms expecting better trading conditions.
What each number measures
A binary event contract has two possible results, determined by whether its stated condition is met or not. Its price can be expressed as a market-implied probability: an estimate derived from trading, rather than a direct measurement of what will happen.
The number does not come from asking every participant whether they agree. It cannot be read as the percentage of traders predicting the event. Survey results also need their definitions. Some surveys ask respondents for probabilities, while others collect numerical forecasts or descriptions of business conditions.
Put the questions side by side

Illustration by Emine Özmen
Imagine a hypothetical contract asking whether the UK’s annual consumer price inflation rate will be below 3% in December 2026, with a market-implied probability of 60%. Both the contract and its quoted probability are illustrative, not a live market observation.
Compare that with the BCC finding: 44% of responding businesses expected their own turnover to improve over the next 12 months. The first statement concerns one national economic outcome. The second counts expectations about thousands of separate businesses.
Those statements can coexist without contradiction. A retailer might expect inflation to ease while anticipating flat sales because a major customer is reducing orders. Another firm could expect higher turnover because it has raised prices, even if it sells no more goods. Turnover is sales revenue, so an expectation of improvement does not automatically mean stronger sales volumes or higher profits.
The 60% estimate does not describe how many businesses benefit from lower inflation. Nor does the 44% response share tell us the probability of crossing the hypothetical inflation threshold.
When reading these assessments, it’s important to pay close attention to wording and define exactly what is being measured and how. If a figure says “below 3%,” that excludes exactly 3%. If it says “3% or below,” it includes it. A figure for December is also different from one published during December. Those are separate questions, and the probability attached to one cannot automatically be substituted for the other.
Dates can change the comparison
Four details make the figures interpretable: the question asked, the respondents or market involved, the observation date, and the period being forecast. Missing any one can create an apparent disagreement that the numbers do not establish.
The BCC responses were collected over several weeks. If a market price is observed in September, it may incorporate information unavailable during that fieldwork. Its later timestamp does not make the earlier survey inaccurate; it means the two readings describe expectations formed at different times.
Forecast horizons matter separately. A condition tied to December is different from a respondent’s outlook over the next 12 months. Even observations recorded on the same day can address different periods. Where dates cannot be aligned, make a note of that rather than presenting the figures as competing answers.
Where your own business fits
Deloitte’s discussion of internal prediction markets emphasises that their signals should be considered alongside other data sources. For an individual business, external economic expectations need to sit alongside the evidence in its own accounts and customer records.
For a London firm assessing next quarter’s sales, confirmed orders, customer renewals, and its own pricing, this approach addresses questions that neither headline percentage resolves. A market estimate about December inflation cannot establish whether a particular customer will renew. A national survey cannot establish the timing of that firm’s receipts.
Keep the external figures attached to their original questions. Before putting either into a company forecast, identify the connection to its customers, costs, or sales. If that connection cannot be explained, the percentage belongs in the background assessment, rather than the revenue calculation.



Leave a Comment