
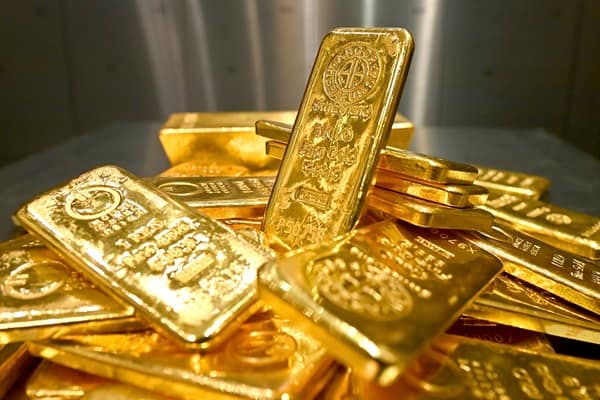
For many retirement investors, a portfolio is made up of a combination of shares, investment funds, bonds and cash.
But times of sustained inflation, market volatility and uncertainty over the value of currencies can lead some to consider putting some of their savings into assets that don’t form part of the conventional financial system.
Precious metals and other tangible assets can form part of an investment strategy for retirement. They won’t necessarily protect against losses or provide an alternative to growth assets, but if you’re concerned about having too much invested in paper assets it may be worth learning more before making any investment decisions.
Why do tangible assets appeal to investors?
The price of a company share is determined by many factors including business performance, management decisions, earnings results and growth prospects. The price of a bar or coin of bullion is driven by different factors including supply and demand, currency values, interest rate expectations and investor sentiment around economic stability.
For investors nervous about the erosion of the value of cash or confidence in financial markets, precious metals can provide comfort as they represent a tangible asset that has been bought, sold, hoarded and accepted as having value throughout history.
That doesn’t mean precious metals are a certainty. Their value can fluctuate wildly and can rise or fall quickly based on investor demand, particularly once fears have abated. Consider precious metals as a potential diversification investment rather than a call on where markets may go.
Their place in a retirement investment strategy
Most investors will want a combination of assets in their retirement investment strategy. Growth assets to try and keep up with the cost of living over time and defensive investments to provide stability when markets fall.
Precious metals sit somewhere else. They won’t provide a return in the form of interest, dividends or rental income, so any return will be based on capital growth – ie you make money if you sell for more than you paid.
However, having a combination of growth investments, defensive investments, cash and some exposure to tangible assets can help avoid a situation where all investments respond to the same market events and potentially provide comfort in unsettled times.
How much you invest will depend on your personal circumstances including when you retire, liquidity requirements, other investments, tax position and risk tolerance.
Tax-effective investment requires the right structure
Many investors assume that if they want to invest in precious metals as part of their retirement strategy they can just buy coins and keep them at home. However, to form part of a tax effective investment strategy the assets would typically need to be purchased in accordance with specific rules and held with a custodian or specialist depository provider.
This isn’t just a technicality – the rules around who can hold the assets, insurance, reporting, charges and whether you can access the assets in future will all be impacted by whether they’re held privately or with a depository provider. It’s also likely that the type of asset purchased will need to meet certain requirements to qualify. Your adviser will be able to advise on the options available.
Be aware that depending on the circumstances there may be a requirement to complete a rollover within 60 days to avoid potential tax implications. It’s important to understand whether money will be transferred straight between providers or paid to you first.
The most important provider questions
Rather than focusing on which coin or bar to buy, the more important decision is likely to be choosing a provider who offers a service you’re happy with and understand. While sales material may paint a picture of simplicity there are actually multiple parties involved – a dealer, custodian and storage provider. If provider comparisons start to blur together, a discussion about choosing the best gold IRA company frames the issues around custody, storage and fees. Some questions you may want to ask a provider before committing include:
- What are the charges and how are they calculated (buying/selling, storage, administration etc)
- Are assets allocated or commingled with other investors’ assets?
- What process would I follow to sell some/all of my holdings and how quickly would I receive funds?
- What assets are permissible within the account?
- Am I aware of the risks as well as benefits of investing in precious metals?
- How will I receive reporting, what insurance is in place and what options do I have if I want my assets delivered?
Especially focus on understanding all of the costs involved as these can eat into any profits you make from an increase in precious metals prices. Ask for all fees, spreads, buying/selling and delivery charges in writing before committing.
Common investment mistakes to avoid
Don’t treat a precious metals investment as your emergency fund. Selling metals and receiving funds may take longer and cost more than selling shares in a fund or withdrawing from a savings account. Keep some cash investments for spending requirements in the short/medium term.
Don’t make decisions based on fear. Particularly when markets are volatile there can be a temptation to act quickly in response to economic news. Consider your objectives, risk appetite and what role you’re expecting an investment to play in your portfolio before committing.
Don’t neglect concentration risk. Investing heavily in one commodity introduces a different risk into your retirement portfolio. Ensure all elements of your portfolio are balanced appropriately.
Questions for your financial adviser
Often investors are attracted to gold and other precious metals as they see them as being relatively unaffected by central bank decisions and company performance. This can form part of the appeal but it’s worth thinking about how an investment will fit into your overall financial position. Some questions worth considering include:
- What am I hoping to achieve from the investment? Protection against inflation, a rainy day fund, long term growth through diversification, a speculative bet? Each comes with different levels of risk and liquidity expectations.
- How do I envisage dealing with the investment once purchased? Leave to grow untouched for years to come or rebalance from time to time?
Physical precious metals can provide an interesting additional element to a retirement portfolio but they don’t absolve you from thinking carefully about investments and keeping an eye on how they’re performing. Don’t be influenced by overly optimistic predictions of precious metals prices. Ask for all information about rollover process, storage/custody agreement and fees in writing before making any decisions about moving retirement savings.
The above information does not constitute any form of advice or recommendation by London Loves Business for investment, nor is it intended as investment advice, financial advice, or trading advice. Appropriate independent advice should be obtained before making any such decision. Don’t invest unless you’re prepared to lose all the money you invest. Take 2 mins to learn more. London Loves Business bears no responsibility for any gains or losses.



Leave a Comment